The word “appraisal” itself is a mystery. It is defined as, “an estimate of value,” but in most cases the value is considered to be for the potential buyer* and may not coincide with what the seller believes is the value. The ski area operator who is considering an appraisal should understand this, as well as the basic elements of realistic appraisals and what to expect of the appraiser so he can position himself to get the most out of the appraisal.
Several articles have been written recently about ski area appraisals. In one, Ted Farwell writes that ski resort appraisals are unique and should be undertaken by specialists in the field. Yet, it seems that almost every appraiser in the country wants to get his hands on a ski resort appraisal because they are “sexy.” Unfortunately, most appraisers (there are a few exceptions) know little or nothing about skiing and have no understanding whatsoever of the unusual problems and potentials related to this industry.
The value of skiing is generally the single most important element in the value of the resort and is the most predictable and dependable (given reasonable weather) over a period of time into the future. Real estate, which wouldn’t be there without the skiing, is of secondary importance and is subject to many more extraneous and uncontrollable variables, such as interest rates, availability of mortgage money, overbuilding by others, etc.* Therefore it is imperative that the appraiser understand the ski area as it exists, identify its problems, and most importantly project reliably what the area’s future potential really is. An informed buyer will look at the future of the area as precisely as how it stands today. In that respect, an appraisal should become a mini-master plan of sorts.
Examples of the unique character of the ski industry abound. It would be interesting to see how an urban-type, computer-oriented appraiser would place a value on some situations we’ve run into in the last couple of years, such as:
- A sewage collection system that is not hooked up to a sewage treatment plant which has never operated and is located on somebody else’s land.
- A ski lift that is in the owner’s equipment shed after having been moved to four different locations on the resort before being “retired,” and is carried on the corporate books at higher than its original acquisition price.
- A sophisticated 10 million gallon snowmaking reservoir that won’t hold water — any water.
- A real estate development which has no water supply, probably can never develop a legal one, and which, although the lots are partially sold, cannot support any construction until the water problem is resolved.
- A subdivision built on land that is approximately 40 per cent owned by other parties.
- A platted real estate development located in the only available parking area for the ski resort.
- A ski lift with drive terminal and 25 per cent of the line located on property owned by another party who refuses to allow operation of the lift.
- Two previous appraisals of the same property done by the same appriser (member of a nationally recognized firm) on the same day with values of $800,000 and $4,500,000 respectively.
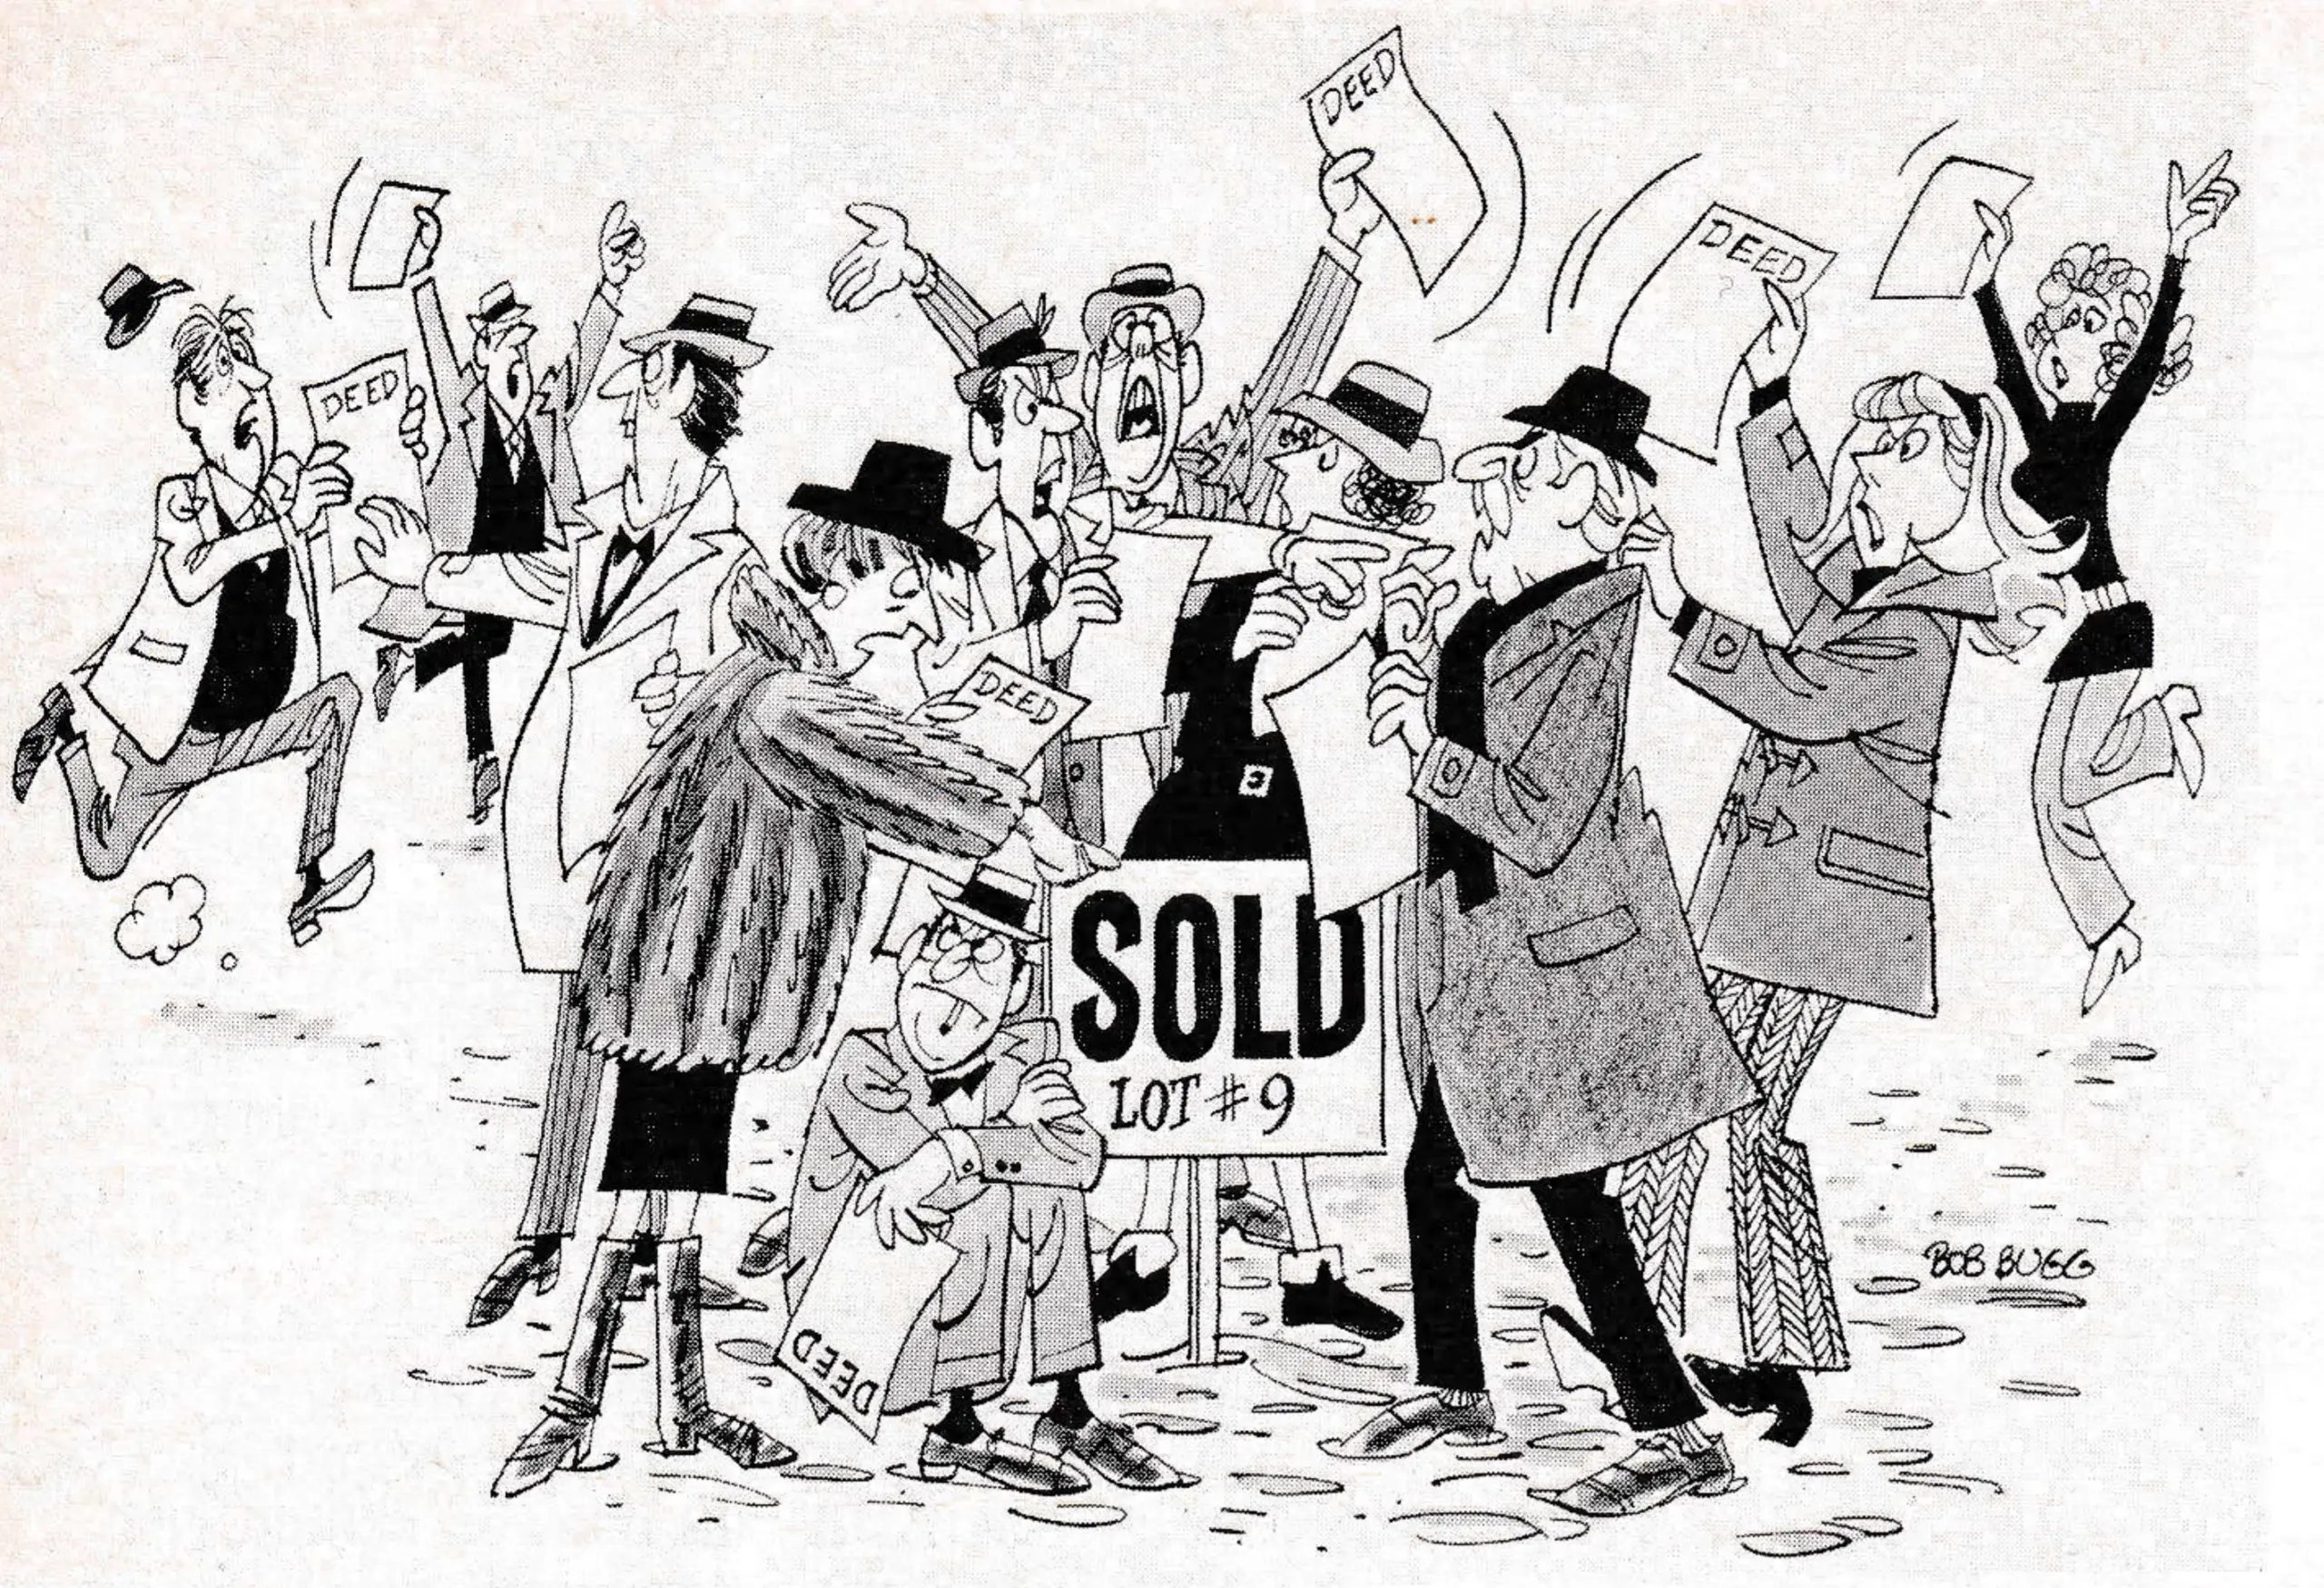
- One particularly nice subdivision lot sold to 11 different owners of record.
- Two surveys of the same area recorded on the same date, one of which was 15 degrees rotated from the other, thereby excluding the lodge, lift drive terminals and water supply from the sales package.
The area owner should understand that he is not actually selling assets per se, but that the buyer is looking at the earning power of the assets. And, there are two elements to that equation: the appraiser must be able to differentiate between asset performance and management performance. Often, the assets are there, are properly maintained and have the potential to produce significant revenue. However, because of sub-standard management performance, or a lack of creativity in marketing programs, the assets have displayed a sub-standard track record. The appraiser cannot specifically point the finger at management, but a perceptive buyer can, in a situation such as this, acquire what appears to be a defunct property, turn it around within a very short period of time and make it into a significant money generator.
The area operator should also understand “Highest and Best Use” and “Market Value.” Highest and Best Use has been defined as “That use which at the time of the appraisal is most likely to produce the greatest net return.” For ski areas it is almost axiomatic that they should be ski areas, but in a few notorious instances we have had to suggest that they be returned to farm or timberland. Market Value is defined as, “The highest price . . . which a property will bring if exposed for sale in the open market, allowing a reasonable time to find a purchaser who buys with full knowledge of all the uses to which it is adapted and for which it is capable of being used.” Most recent ski area sales have either been distress circumstances, are based in part on internal manipulation, or include a significant amount of real estate which generally muddies the main issue of “what is the skiing worth?” However, several recent transactions reflect a marketplace where buyer and seller can deal at arms length.
With that thought in mind, we would like to point out some things which an area operator should not expect from the appraisal and some which he definitely should.
Do not expect:
- The appraiser to develop all original data. You must supply him with valid information.
- To be reimbursed for your mistakes.
- A realistic value based on replacement cost only.
- An appraisal based strictly on book value.
- A value based on projecting all unsold real estate at its historic high value, at lowest development cost, and at maximum sales rates.
- The appraiser to overlook significant negative elements or planning errors, such as an unrealistic economic projection of 10,000 beds for a mountain with 1,500 comfortable capacity.
- The appraiser to produce a sales document.
- A totally unqualified appraisal. All appraisals have limiting conditions imposed on them.
On the other hand, a knowledgeable area operator should expect:
- To be given credit for “going concern value” of his area. A leading accounting firm has this to say about going concern value; “Going Concern Value . . . . can be based on revenues, costs and net operating losses, and, return on investment foregone during a representative start-up period.”
- Credit or value added for the “equity value” of leases on land which generate income. Very often the lease which you hold on the land for your area has a greater value relatively speaking than the rental fee which has historically been paid. This differential can be classified as an equity element in the evaluation of your area.
- A value which reflects his local competitive advantage. With ski areas, it is seldom that a competitor can geographically come between you and your market as is the case with gas stations where someone can usually buy a “better corner.”
- An increased value for land devoted to skiing over and above that which was originally paid or in relation to adjacent raw timber or open land prices. A formula exists for valuing ski trails based on their earning power potential.
- Value added which reflects planning and efforts in assembling and packaging the land which makes up the resort. After all, ski areas cannot be located on just any hillside acreage.
- To be given credit for the value of the proximity of his land to the ski center focus and the contiguity of his land package.
In summary, if you are considering an appraisal for any reason, be sure that you get the most from it by employing a professional who understands the business and can produce a “mini-master plan”: by discussing the intent of the appraisal well ahead of time; by providing full and reliable information; and by making sure that the appraiser understands not only what your area is now but what it can be in the future.
*This is not always true. Appraisals may be needed in connection with property transfers, in connection with financing and credit, to establish an equitable tax base, to determine insurable value, or for condemnations/foreclosures.
*However, we must admit that a knowledgeable investor from the U.S. may have an idea of what “value” is for a particular area, whereas investors from overseas may, because of their interest in U.S. real estate, be willing to pay a premium for the same resort.