

Have You Analyzed Your Accounting Procedure?
Ski areas typically require a large capital investment in fixed assets to generate what is a relatively modest cash flow. The consequence is that, although depreciation is a non-cash expense item, it accounts for a major portion of annual operating expenses. In addition, the use of artificially created short lives for assets elevates depreciation to a level demanding close analysis.
Just what is depreciation and what is its role in determining the profitability of a ski area?
Generally, depreciation is a method of recovering invested capital. The two important elements are: 1) determining the useful life of an asset; and 2) selecting the mathematical method for accounting procedures. Engineers tend to view the life of an asset by its physical properties, that is, how long before it wears out. Economists, on the other hand, use a concept embodying obsolescence or “economic” life, which is the time an asset has “earning power.”
In order to discuss depreciation, it will be useful to digress and look at the financial objectives of management. Investors want a return on their capital and modern methods of calculating a return place emphasis upon the “time value” of money. Once a ski area is built, the investment or capital is committed and sunk. Management is now interested in a rapid recovery and tries to maximize the annual cash flow. Their financial objective is to establish a maximum cash flow as early in the life of the ski development as is possible. Under the present income tax laws, a large non-cash expense like depreciation plays an important role in establishing an early cash flow.
Estimating a useful economic life for lifts, trails, buildings and equipment is the major debatable area in depreciation. Because income tax considerations are so important in depreciation, a look at guide lines established by the Internal Revenue Service serves as a point of departure.
Revenue procedure 62-21, “Depreciation Guide Lines and Rules,” contains information of importance to ski area operators. But it establishes no specific rules for the life of assets used in ski areas. In fact, a note on page 86 excludes “ski slopes and related facilities, the depreciable lifes of which shall be determined according to the facts and circumstances.” You are allowed to depreciate a piece of equipment over the length of the period it is of use to you.
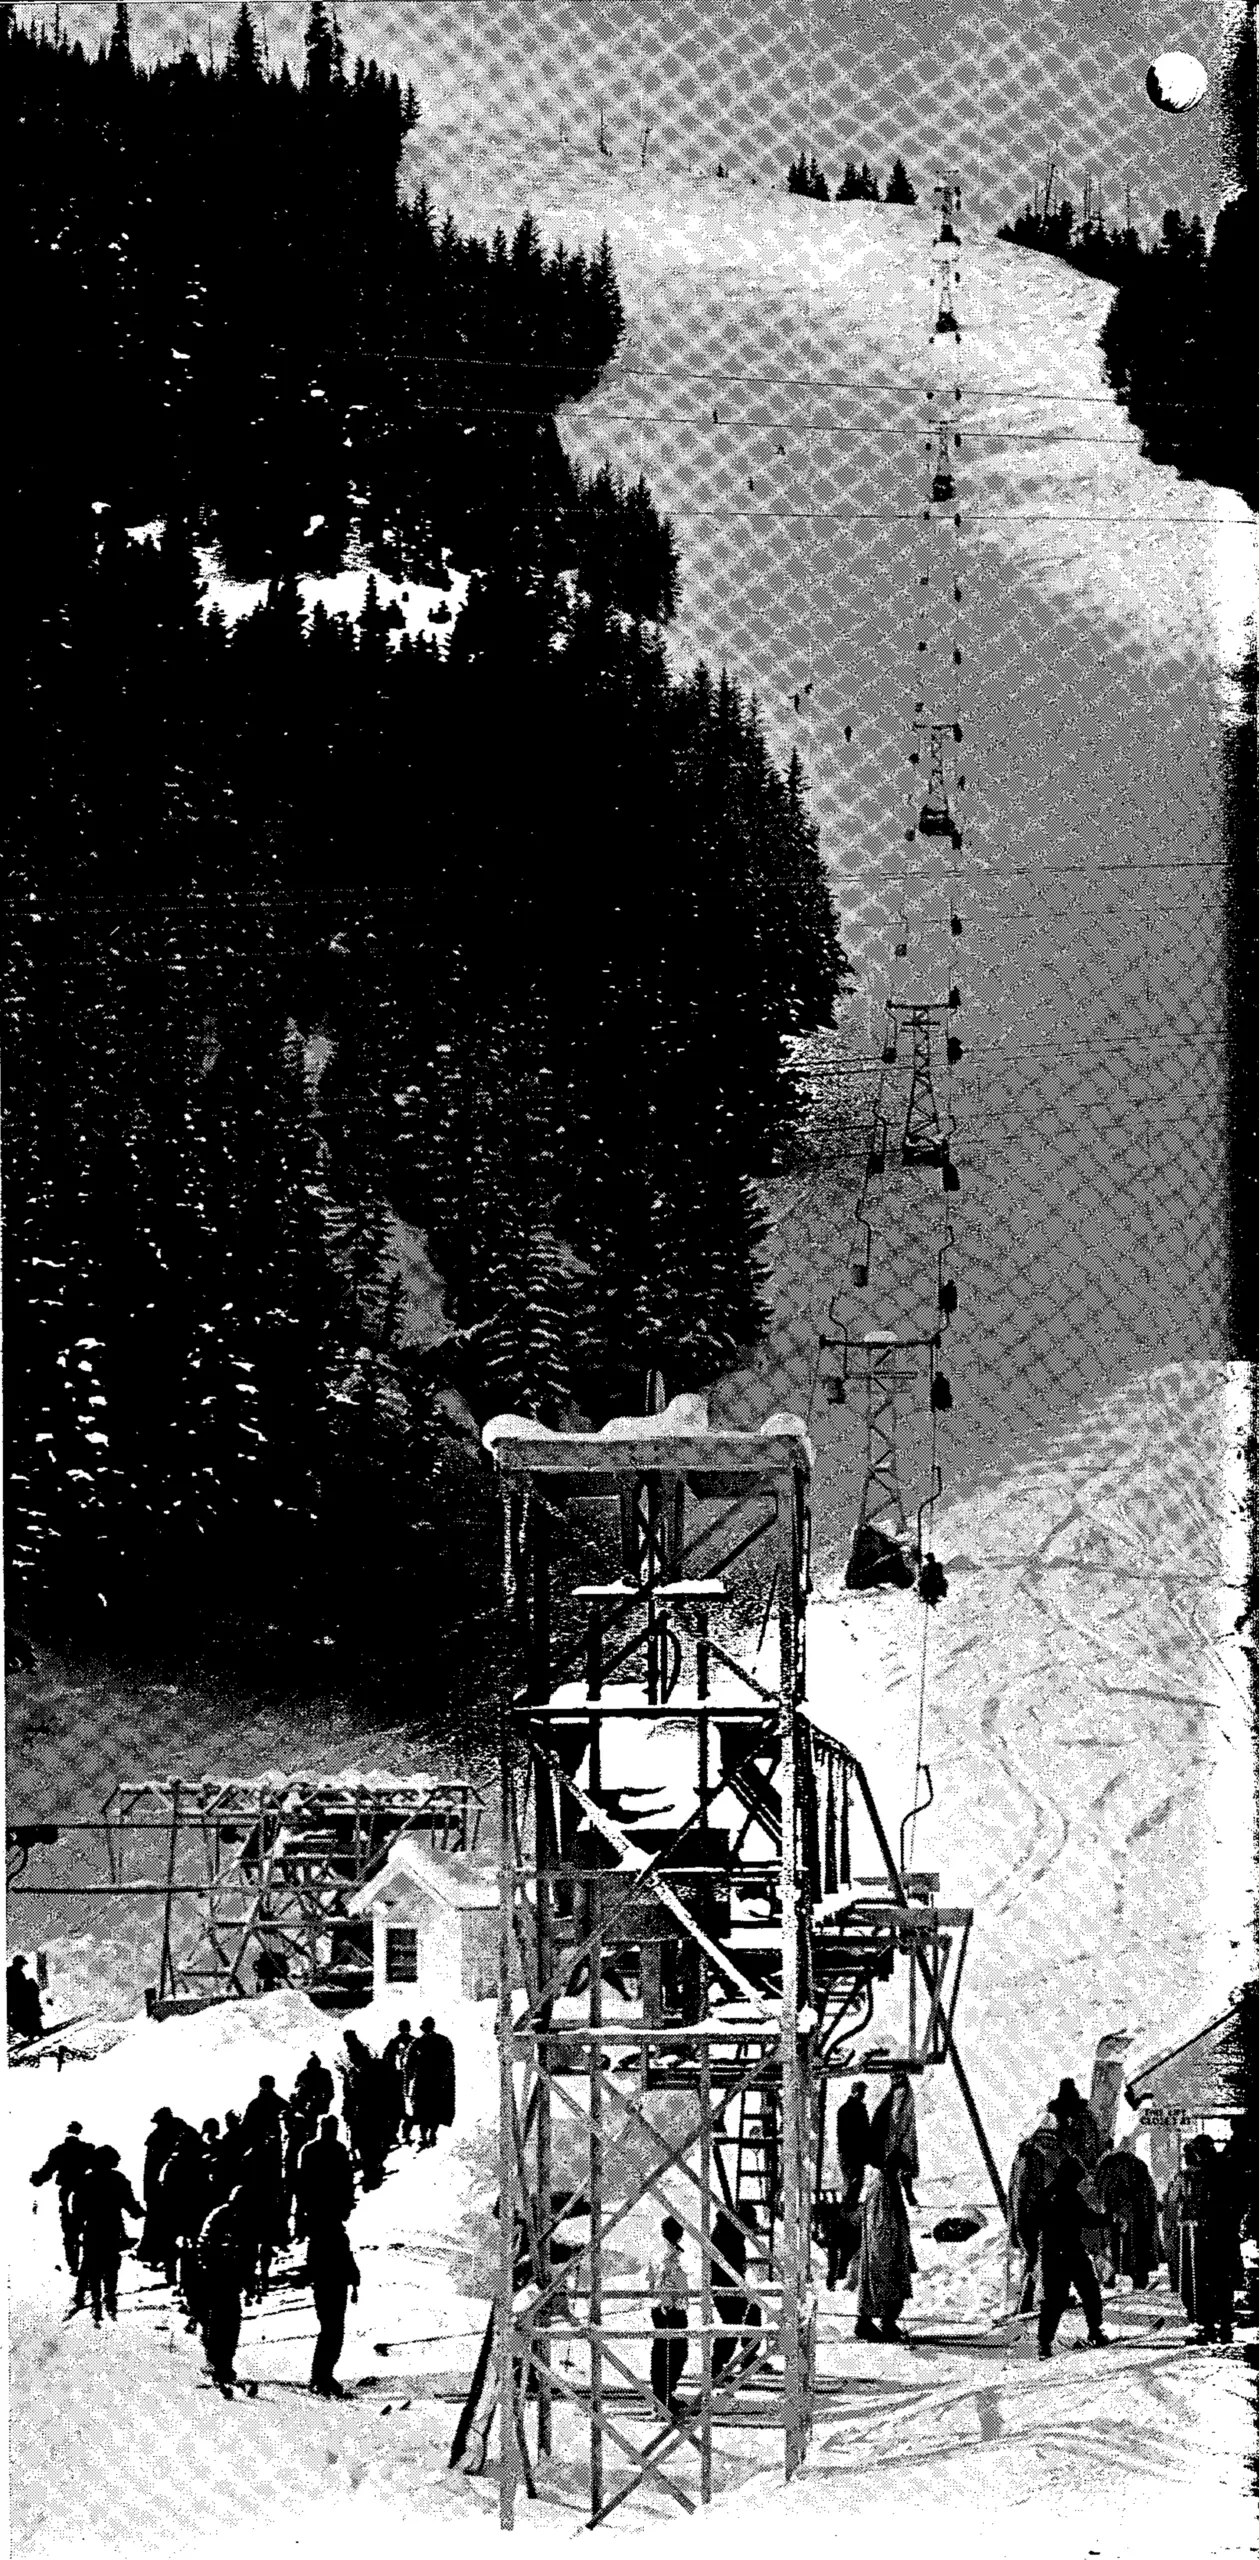
While equipment, furniture, etc., are rather easy to handle, more permanent things such as your ski lifts present somewhat of a different problem. What is the economic life of a ski lift? The structural life and soundness of the various parts can be reasonably estimated by an engineer. He may find that the life of the original towers is 40 years but you probably will have replaced everything else in that period of time. Proper depreciation procedure would, therefore, call for you to establish replacement policies based on the engineer’s estimate of the life of various component parts, obtain an average life, lump all component parts and all lifts into one account and depreciate these over the average life. A survey of ski operators reveals the present estimated life of ski lifts varies from ten to fifteen years.
However, what does this tell us about the “economic” life of a ski lift? Will a lift have earning power over 10-15 years? Will technological improvements (i.e., triple and quadruple chairs, 1400/hr. gondolas, multiple loading platforms, etc.) make equipment obsolete before these years pass? And if so, can you program these events, thus supporting a shorter “economic” life?
Much work has been done in this area in other businesses, particularly those undergoing rapid technological change, and perhaps a project designed to establish ski industry norms would pay dividends. A logical argument can be made in support of shorter economic lives for assets used in providing skiers with winter recreation.
Any accounting text or reference carries an explanation of the various methods of depreciating. Accelerated methods are preferred if income and the resulting cash flow is large. Conversely, using accelerated methods with a very poor cash flow could cause a continual loss situation. Aside from the demoralizing effect such a picture has on stockholders, there is a possibility, if the situation persists, that the business could lose its ability to write off past losses against present gains and place itself in an undesirable tax situation.
Because losses may be carried forward five years or back three years, it should be recognized that accelerated methods of depreciation merely postpone the time when income taxes must be paid. This means that depreciation taken in earlier years is not available in later years. Thus, assuming a steady cash flow, as depreciation expense decreases, income tax liability increases. It must be noted that this procedure results in a larger total return to investors, because they received a higher percent of the cash flow in the earlier years of the development.
Accelerated methods of depreciation and the “economic” life of an asset are not universally accepted by business men. The concept of valuing an investment as a function of the cash flow it can generate, instead of looking at the book profit shown on the annual statement, is the key to understanding the logic behind these methods of accounting for depreciation.
Mr. Farwell is research director of Sno-Engineering Inc., Franconia, N. H.
Lift Write-Off: IRS Is Unfair.
By F. D. Voorhees
In recent years debate has run high on the question of whether the Internal Revenue Service is justified in forcing long term depreciation schedules on ski lift operators. The basic policy of the IRS is that the burden of proof for any fast write-off is the responsibility of the taxpayer. However, the IRS not only lacks continuity in their approach to the matter, they also lack experts in the specific field of skiing. The result is, what may be allowed by one examiner may be rejected by another in the same district.
Lack of knowledge of the ski industry as well as application of general rules that are incompatible with the specific requirements of the industry seem to be the main reasons for this situation. The government doesn’t accept the fact that the industry economics preclude providing facilities to handle peak crowds. The fact that new equipment must be continually added to increase efficiency and to maintain a competitive position (thus relegating older marginal equipment to standby status) does not render the older equipment obsolete in the eyes of IRS. Further, lift utilization may become marginal even while relatively new due to technological advances. But, according to the IRS, equipment is not obsolete until people are unwilling to ride it. Lifts must be abandoned or removed if they are so sub-marginal that they may no longer be considered an asset.
Accordingly, there exists a tax concept incompatible with the economics of the industry. Operators are forced to depreciate on schedules which are inconsistent with both their actual needs and their financial philosophy.
One of the most unsettling IRS practices is to review a schedule in the latter years of its life and force an extension of the term. In one case not long ago, a review was initiated by the IRS in the ninth year of a ten-year life schedule on a well-known western area. The government’s position was that even though the particular chairlift in question was about ten years old and had been far surpassed in terms of technological improvements, it was still running well and the tax life should be extended for another ten years. A compromise was reached allowing the schedule to be reduced from 20 to 15 years. Even so the operator reportedly paid more than $25,000 in adjustable back income taxes.
The question boils down to this: can you afford to stand idle while your competitors increase lift capacity—and their revenue—simply because your five-year-old lifts still have ten years of alleged usable life? Few area operators can. Even though the short life write-off option is not unanimously accepted in the industry, enough operators want it to justify investigating tax charges. The IRS needs to recognize that lifts can be allowed a quick write-off because they become obsolete by technological advancement.
Obsolescence occurs whenever any manufacturer makes a design modification which increases capacity, efficiency or safety. Consider the impact on passenger convenience and operating costs of rubber lined sheaves which may be relined in the field, derail-resistant sheave flanges, bumpless, quick, detachable grips, ice prevention on chair seats, gondolas vs. chair capes, factory lubricated sealed bearings, the increase in ratio of passengers to operation, etc. The majority of these improvements have occurred within the past ten years, rendering many lifts obsolete in terms of skier acceptance and operating costs.
The IRS may claim that a sub-standard lift can be up-graded. But in many instances, modifications are not possible because they are incompatible with the initial design concept.
The rapport between the IRS and the industry must be improved. IRS must appreciate the operators’ problem and establish a standard interpretation of the code as it applies to ski lift equipment per se. A generalized code with as many interpretations as there are tax districts simply will not do. The same standard must be employed throughout the entire country. Among other points, the IRS should clarify the following:
- What constitutes a reasonable depreciation allowance as defined in the obsolescence law?
- What represents a reasonable salvage value?
- Is economic obsolescence allowable?
- Is design obsolescence allowable?
- When technological improvements increase safety can this be allowed?
If the answer to any of the foregoing questions is “no,” which seems likely, then the IRS should justify its position. The burden of proof for fluctuating and ambiguous interpretations should not rest entirely on the ski area operator.
There is, however, one partial solution to the problem. An agreement could be made between the IRS and the operators to leave the depreciation schedule undisturbed during the first five years of its life. The shortcoming of this approach is that a lift must be installed prior to the execution of such an agreement and after the five-year statute expires the operator is again on thin ice. To resolve this aspect of the problem, the IRS could allow an agreement to be executed prior to placing the lift. Further, the agreement could be extended beyond the first five years.
Another need is for a regulation to allow an operator to decrease the depreciation term based, of course, on just cause. A case in point is when an inexperienced operator establishes a 15-year schedule for a particular type of lift. The fact that the lift may not have a usable life of more than ten years puts the operator at a serious disadvantage. His original error in setting up the schedule also establishes a precedent for future installations. Just as the IRS can increase a schedule, the operator should be allowed to decrease it when justified.
Much has been written about the low earnings of lift operation. This is hard to accept in a broad sense, but if it is true, might the IRS then be obstructing future expansion?
The ski industry needs tax relief now. NSAA should not delay in approaching the IRS. Failure will not only affect industry members but the skiing and recreational public as a whole.
Mr. Voorhees is director of resort planning for American Resort Consultants, Inc., Renton, Washington.

