

What does one say about a lift-building year that is not exactly, er, uplifting? I guess you just supply the facts and leave the adjectives to the reader. But first, let me bring one of the last items in this reportage right up to the front: the big news—the bit with the red meat—is not in some exotic new funitel or other major lift installation but in the proliferation in conveyor lifts. It’s an important direction the industry is taking: We’re building a future! More on this further on.
This year’s actual lift construction figures look alarmingly like last year’s: a total of 35 new lifts—up a smidgen from 33, but yielding a total new VTFH of 56,646, down from last year’s 67,081.
Those 35 new lifts break out a little differently in terms of geography and configuration, but not that much. Reflecting the fine snow season enjoyed by the East, that region added 13 new lifts, compared to 10 the year before. On the flip side, the Pacific region areas, coming off a rather poor snow year, managed only one-half of last year’s six new installations. The Midwest doubled (but that still only meant four new lifts), while the Mountain states dropped from five to four. Canada stayed about even.
As for the type of lifts being installed, they are all chairs: four of them 6-packs, 25 quads and six triples. For the first time ever, no doubles; for the second time ever, there were no surface lifts built.
There was one chondola installed (see November SAM on the hybrid chair(6)/gondola(8) at Mont Orford, Quebec). For the record, we included the chair part of this exotic lift in the stats for our chairlift computations.
Of all the installations, 16 are detachables. Expressed as percentages, this year’s 46 percent detachable is essentially the same as last year’s 47 percent.
Also unchanged from last year is the high proportion of new installations that are replacement lifts. True, the percentage dropped a bit (from 64 to 54 percent), but the proportion is still high.
And why wouldn’t it be? Let’s face it, brand new areas and terrain expansion are about the only conditions that immediately mandate lift construction, but how much of either do we see these days? Yes, we actually have one this year, Moonlight Basin in Montana, but it’s a rarity, and a welcome one at that.
On the other hand, if you think of the 958 chairlifts installed in the decade of the 1970s and realize that the survivors today are 30 years old or approaching it, you realize how much potential business must be out there—old iron just waiting to be replaced.
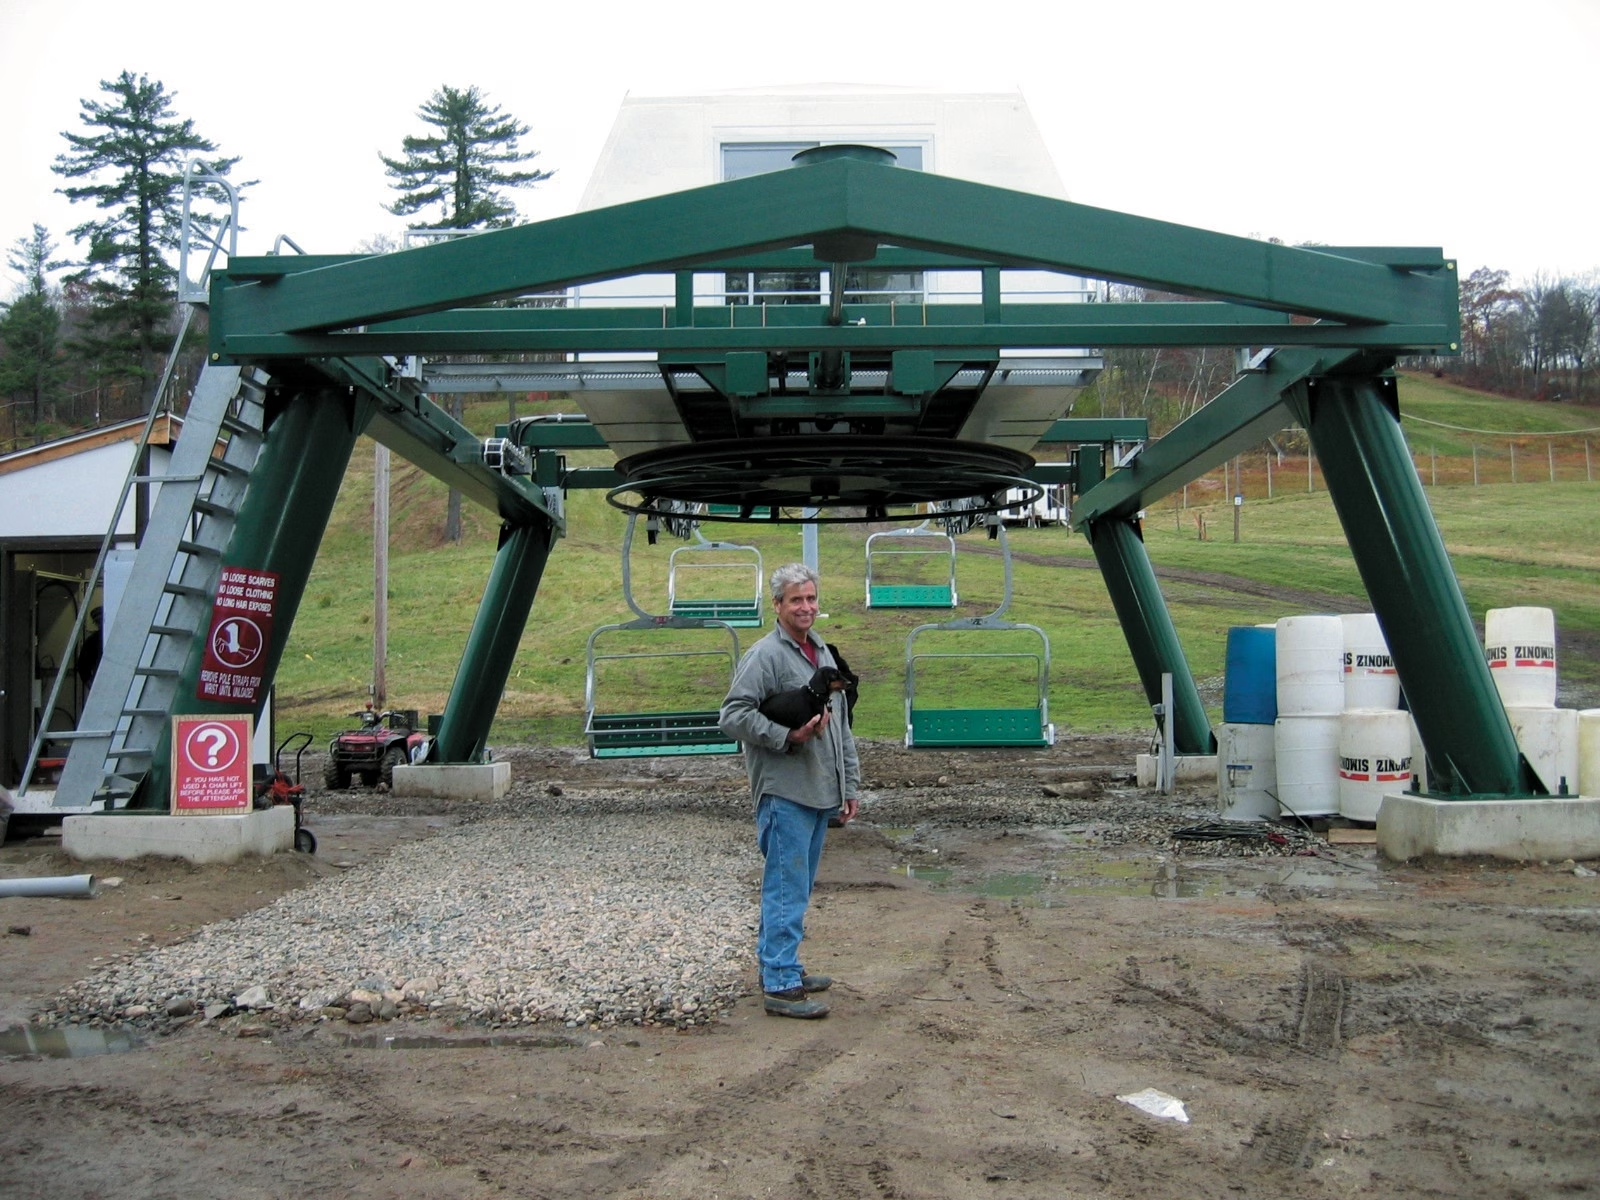
Carrying this salivating thought one step further, consider that in the Midwest alone between 1978 and 1979, 37 chairlifts were installed, 23 of them quads. In 1972 alone, no less than 36 chairlifts were installed in the Midwest!
So why isn’t there more replacement business? This year there were four chairs installed in the Midwest, but only one of them was a replacement. It’s a puzzlement. Hagen Schultz, of Partek Lifts, thinks it is a market segment that will drive lift construction in the years ahead. Doppelmayr CTEC’s Jan Leonard would like to agree, but he points to the durability of the old Halls and Borvigs and gives a tip of the hat to the areas that keep taping them together and keep running them safely and successfully. Besides, he adds, where is the incentive to replace them? Where’s the new revenue going to come from to pay for the spiffy new lift? Customer numbers haven’t changed and there’s little or no upward flexibility in ticket pricing.
Leitner-Poma’s Rick Spear takes the long view of what is happening. He thinks the industry emphasis on retention and getting kids on skis is key to the long-term future. Lift-building will come with demand-building, and that won’t happen until the industry makes sure there is a steady flow of kids entering as snow-sliders who will become tomorrow’s skiers and boarders. In the meantime, though, he’s concentrating on the twin concepts of advancing technology and keeping prices down. “I’ll be scrapping for every piece of business there is,” he promises as he looks to bounce back from the competitive set-back he has had in relation to the other giant, Doppelmayr CTEC. Reminded that a year ago the shoe was on the other foot, Spear acknowledges, “Yeah, it does seem to go back and forth between us from year to year. It tends to even out.” (For the record, Doppelmayr CTEC got 72 percent of the total VTFH this year and Leitner Poma 23 percent. Last year, Doppelmayr CTEC only had 54 percent of new VTFH, while Leitner Poma had jumped from 18 percent the previous year to 42 percent. As the man said, it sort of goes back and forth.)
In the manufacturer stakes, it would be hard to bet against is Partek Lifts, the familial and engineering successor to Borvig, for future growth. With Riblet Tramway out of the picture, Partek is in a position to be nimble and price-responsive to ski area needs in a way that the two giants would like to, but may not always be able to. This year Partek was able to notch six solid fixed-grip lifts on its corporate holster—three quads and three triples. Lest there be any doubt, they are delighted to bid on detachables, too.

Still another insight into the lift-buying comes from seeing how much of the total is accounted for by the big, multi-resort conglomerates as compared to the independents. The numbers are inconclusive insofar as being able to spot trends. It’s impossible to generalize from the specific buying incentives involved.
For instance, the fact that American Skiing Company has bought no new lifts for its eight major ski resorts for the second year in a row speaks to its corporate debt service rather than to market forces. At the other end of the scale, Vail Resorts plunged in with two installations at their newly acquired Heavenly Resort and found financial justification in a 5,611 VTFH (biggest lift of the year) detachable quad at Beaver Creek. Booth Creek added no new lifts to its resorts (good snow in the East could not offset the opposite in the Pacific region), while Intrawest was cautious in its lift-building, limiting it to a couple of detachable quads at Panorama, B.C. and a purposeful 6-pack at Blue Mountain, Ont.
The numbers, therefore, show the big four conglomerates accounting for 30 percent of this year’s new VTFH; this is substantially up from the 13 percent last year, while still well below the 43 percent in the conglomerate binge of 1997. But, as remarked above, this measure of conglomerate vs. independent areas is probably not meaningful.
Perhaps the most upbeat set of numbers coming out of this year’s new lift stats is the dramatic increase in the conveyor category. This represents huge progress that bodes well for future growth. It represents a commitment to bringing kids—and more kids—into the sport, as well as a commitment to work on converting all beginners into long-term enthusiasts. All this can be seen as validation of NSAA’s Growth Model.
Look at the numbers: We count no less than 61 new conveyor-type lifts. In just three years, we have seen this category go from 37 to 46 to 61. That’s some growth! Interestingly, it may have been partially at the expense of other uphill devices that often serve beginner needs, like wire ropetows, handle tows and the like. But the larger significance of these figures is the reflection of the industry’s determination to grow the sport from the ground up‚ with kids.
Finally, as we always do, we acknowledge that our areas make huge investments in upgrading existing lift equipment. This not only helps our industry maintain its enviable safety record, but it helps provide those good up-ski experiences that we need as part of the mix. As in the past, these upgrades are not included in the lift construction totals on these pages.
New Lifts by Manufacturer
| Manufacturer | Surface | Chair | Gondolas/Trams | Total lifts | Total VTFH |
|---|---|---|---|---|---|
| Doppelmayr CTEC | — | 22 | 1 | 22 | 41,051 |
| Leitner-Poma | — | 7 | — | 7 | 12,978 |
| Partek | — | 6 | — | 6 | 2,617 |
| Totals | — | 35 | 1 | 35 | 56,646 |
¨ Mont Orford chondola listed under both Chairs and Gondolas/Trams but counted only once in totals.
New Lifts by Region
| Region | New VTFH | Surface | Chairs | Gondolas/Trams | Total |
|---|---|---|---|---|---|
| East | 12,431 | — | 13 | — | 13 |
| Midwest | 3,120 | — | 4 | — | 4 |
| Mountain | 13,376 | — | 4 | — | 4 |
| Pacific | 6,425 | — | 3 | – | 3 |
| Canada | 21,294 | — | 11 | 1 | 11 |
| Totals | 56,646 | — | 35 | 1 | 35 |
¨ Mont Orford chondola listed under both Chairs and Gondolas/Trams but counted only once in totals.
VTFH Comparison with Preceding Years
| Region | 1994 | 1995 | 1996 | 1997 | 1998 | 1999 | 2000 | 2001 | 2002 | 2003 |
|---|---|---|---|---|---|---|---|---|---|---|
| East | 31,603 | 31,781 | 15,890 | 32,123 | 19,453 | 33,695 | 11,358 | 16,881 | 14,891 | 12,431 |
| Midwest | 866 | 1,069 | 95 | 5,929 | 2,185 | 4,373 | 1,070 | 0 | 1,744 | 3,120 |
| Mountain | 28,807 | 19,676 | 59,195 | 71,199 | 69,922 | 52,591 | 21,999 | 25,625 | 12,906 | 13,376 |
| Pacific | 22,645 | 11,916 | 28,549 | 22,088 | 46,357 | 17,952 | 28,521 | 4,091 | 11,296 | 6,425 |
| Canada | 24,034 | 15,430 | 16,444 | 15,232 | 28,265 | 22,142 | 32,424 | 18,042 | 26,244 | 21,294 |
| Totals | 107,955 | 79,872 | 120,173 | 146,571 | 166,182 | 130,753 | 95,372 | 64,639 | 67,081 | 56,646 |
Lift Comparison with Preceding Years
| Region | 1994 | 1995 | 1996 | 1997 | 1998 | 1999 | 2000 | 2001 | 2002 | 2003 |
|---|---|---|---|---|---|---|---|---|---|---|
| East | 15 | 13 | 11 | 12 | 10 | 13 | 6 | 12 | 10 | 13 |
| Midwest | 1 | 4 | 1 | 10 | 3 | 4 | 2 | 0 | 2 | 4 |
| Mountain | 13 | 12 | 24 | 24 | 21 | 25 | 11 | 14 | 5 | 4 |
| Pacific | 9 | 5 | 10 | 9 | 17 | 10 | 10 | 2 | 6 | 3 |
| Canada | 13 | 7 | 7 | 6 | 13 | 11 | 21 | 9 | 10 | 11 |
| Totals | 51 | 41 | 53 | 61 | 64 | 63 | 50 | 37 | 33 | 35 |
Conveyors*
| Manufacturer | Lifts |
|---|---|
| Kaser Skicarpet NA | 17 |
| Magic Carpet | 15 |
| Schippers | 7 |
| Star Lifts | 22 |
| TOTAL | 61 |
Tows: Rope, Handle, Wire Rope*
| Manufacturer | Lifts |
|---|---|
| Harusch | 3 |
| Multi Skilift | 6 |
| Schippers | 5 |
| Star Lifts** | 11 |
| TOTAL | 25 |
*Not included in lift statistics.
**Includes Borer, Brückschlögl and O’Connor.
New Lifts Installed in 2003
East
| Location | Type | Manufacturer | HP | Installed Length | Vert. | Cap. | Speed | VTFH (000) |
|---|---|---|---|---|---|---|---|---|
| MARYLAND | ||||||||
| Wisp – Deep Creek | 3C | Doppelmayr CTEC | 150 | 3170 | 568 | 1500 | 465 | 852 |
| Wisp – Deep Creek | 3C | Doppelmayr CTEC | 150 | 3170 | 568 | 1500 | 465 | 852 |
| MASSACHUSETTS | ||||||||
| Bradford | 3C | Partek | 60 | 995 | 200 | 1800 | 400 | 360 |
| Ski Ward | 3C | Partek | 60 | 1105 | 178 | 1425 | 400 | 254 |
| NEW HAMPSHIRE | ||||||||
| Bretton Woods | 4C-Det. | Doppelmayr CTEC | 400 | 2455 | 556 | 2800 | 1100 | 1557 |
| Cannon Mountain | 4C | Doppelmayr CTEC | 100 | 1324 | 281 | 2400 | 400 | 674 |
| Gunstock | 4C-Det. | Doppelmayr CTEC | 600 | 6427 | 1602 | 2400 | 1000 | 3845 |
| Pats Peak | 3C | Partek | 250 | 2097 | 359 | 1500 | 425 | 539 |
| NEW YORK | ||||||||
| Holiday Valley | 4C-Det. | Doppelmayr CTEC | 300 | 2669 | 477 | 2400 | 1000 | 1145 |
| Holiday Valley | 4C | Doppelmayr CTEC | 40 | 872 | 127 | 1500 | 300 | 191 |
| PENNSYLVANIA | ||||||||
| Bear Creek | 4C | Doppelmayr CTEC | 125 | 2781 | 430 | 1800 | 450 | 774 |
| VERMONT | ||||||||
| Okemo | 4C-Det. | Leitner-Poma | 250 | 2530 | 390 | 2400 | 1000 | 936 |
| VIRGINIA | ||||||||
| Massanutten | 4C | Partek | 100 | 2368 | 226 | 2000 | 400 | 452 |
Midwest
| Location | Type | Manufacturer | HP | Installed Length | Vert. | Cap. | Speed | VTFH (000) |
|---|---|---|---|---|---|---|---|---|
| MICHIGAN | ||||||||
| Crystal Mountain | 4C | Doppelmayr CTEC | 100 | 1161 | 226 | 2400 | 410 | 542 |
| Pine Knob | 3C | Doppelmayr CTEC | 40 | 820 | 135 | 1200 | 350 | 162 |
| MISSOURI | ||||||||
| Hidden Valley | 4C | Partek | 100 | 1383 | 308 | 1800 | 400 | 554 |
| WISCONSIN | ||||||||
| Granite | 6C-Det. | Leitner-Poma | 400 | 3260 | 582 | 3200 | 1000 | 1862 |
Mountain
| Location | Type | Manufacturer | HP | Installed Length | Vert. | Cap. | Speed | VTFH (000) |
|---|---|---|---|---|---|---|---|---|
| COLORADO | ||||||||
| Aspen Mountain | 4C-Det. | Leitner-Poma | 500 | 4689 | 1120 | 2400 | 1000 | 2688 |
| Beaver Creek | 4C-Det. | Doppelmayr CTEC | 900 | 6453 | 2158 | 2600 | 1000 | 5611 |
| MONTANA | ||||||||
| Moonlight Basin¨ | 6C-Det. | Doppelmayr CTEC | 900 | 8700 | 1828 | 2425 | 1050 | 4433 |
| Moonlight Basin¨ | 4C | Doppelmayr CTEC | 100 | 2544 | 429 | 1500 | 425 | 644 |
Pacific
| Location | Type | Manufacturer | HP | Installed Length | Vert. | Cap. | Speed | VTFH (000) |
|---|---|---|---|---|---|---|---|---|
| CALIFORNIA | ||||||||
| Heavenly | 4C-Det. | Doppelmayr CTEC | 500 | 3831 | 1002 | 2600 | 1000 | 2605 |
| Heavenly | 4C | Doppelmayr CTEC | 60 | 910 | 172 | 1600 | 350 | 275 |
| NEVADA | ||||||||
| Diamond Peak | 4C-Det. | Doppelmayr CTEC | 600 | 4923 | 1477 | 2400 | 1000 | 3545 |
Canada
| Location | Type | Manufacturer | HP | Installed Length | Vert. | Cap. | Speed | VTFH (000) |
|---|---|---|---|---|---|---|---|---|
| ALBERTA | ||||||||
| Sunshine Village | 4C-Det. | Leitner-Poma | 400 | 2854 | 705 | 2400 | 1000 | 1692 |
| BRITISH COLUMBIA | ||||||||
| Grouse Mountain | 4C-Det. | Leitner-Poma | 450 | 2820 | 1176 | 2300 | 1000 | 2705 |
| Panorama | 4C-Det. | Doppelmayr CTEC | 800 | 6347 | 2062 | 2400 | 984 | 4949 |
| Panorama | 4C | Doppelmayr CTEC | 160 | 2923 | 922 | 1200 | 453 | 1106 |
| ONTARIO | ||||||||
| Alpine Ski Club | 4C | Doppelmayr CTEC | 200 | 1529 | 535 | 1800 | 453 | 963 |
| Blue Mountain | 6C-Det. | Leitner-Poma | 500 | 2955 | 717 | 3600 | 1000 | 2581 |
| Hockley Valley | 4C | Leitner-Poma | 100 | 908 | 214 | 2400 | 453 | 514 |
| Horseshoe Valley | 4C | Partek | 100 | 1440 | 229 | 2000 | 450 | 458 |
| London Ski Club | 4C | Doppelmayr CTEC | 50 | 666 | 113 | 2400 | 350 | 271 |
| QUEBEC | ||||||||
| Bromont | 4C-Det. | Doppelmayr CTEC | 500 | 3645 | 981 | 2400 | 984 | 2354 |
| Mont Orford | 6/8 Chondola | Doppelmayr CTEC | 800 | 5322 | 1542 | 2400 | 984 | 3701 |
| ¨ New ski area |

